Skip to content
Click to Call Send us a Text
HomeSale Insurance Services

Pennsylvania Office
215 S Centerville Rd,
Lancaster, PA 17603

Get Directions

Maryland Office
1425 Clarkview Rd,
Baltimore, MD 21209

Get Directions

Get a Quote

Start your free quote now!

Cannonballs and Coverage: Is Your Home Insurance Ready?

As the temperatures climb in Lancaster and Baltimore, many of us are busy uncovering the pool and prepping the patio for summer BBQs. Before the first cannonball hits the water, make sure your homeowners’ insurance is ready. Learn how to protect your pool, guests, and assets this summer.

1. The Liability “Safety Net”
Most standard Home Insurance policies include a baseline of liability coverage. This is what protects you if a guest is injured on your property. However, with a pool, the stakes are higher.

The Recommendation: Most experts suggest increasing your liability limits to at least $300,000 or $500,000 if you own a pool.

The Umbrella Option: For ultimate peace of mind, an Umbrella Insurance policy provides an extra layer of protection (usually $1 million or more) that kicks in after your home policy is exhausted.

2. Safety Requirements & Your Premium
Insurance carriers often have specific requirements to ensure your pool is as safe as possible. Failing to meet these could result in a denied claim or a canceled policy.

Fencing: Most carriers (and local PA/MD ordinances) require a fence at least 4 feet high with a self-closing, self-latching gate.

Diving Boards & Slides: Be aware that some insurers may exclude coverage for injuries related to diving boards or slides, or they may refuse to insure homes that have them.

Maintenance: Ensure your pool deck is non-slip and free of tripping hazards to prevent the most common “slip and fall” claims.

3. Don’t Forget the “Physical Damage”
Liability isn’t the only concern. What happens if a severe summer storm knocks a tree onto your pool or destroys your expensive filtration system?

Other Structures: Typically, your pool is covered under “Coverage B” (Other Structures) of your homeowners policy. It is worth checking to see if your current limit is high enough to replace the pool and surrounding deck in the event of a total loss.

Enjoy the Summer with Confidence
At HomeSale Insurance Services, we want you to enjoy your summer without worrying about “what ifs.” Whether you are installing a new pool this year or just opening up an old favorite, we can review your current policy to ensure you have the right protection at the best possible rate.


Call us today at 1-800-425-5130 or visit our website at www.homesaleinsurance.com
5 Essential Road Trip Tips for a Stress-Free Vacation

Planning a summer getaway? From car maintenance to umbrella policies, here are the top 5 insurance essentials every PA and MD driver needs for a safe road trip.

Before you load up the cooler and queue the playlist, run through this quick checklist to ensure your trip is memorable for all the right reasons.

1. The “Under the Hood” Basics
It sounds simple, but most breakdowns are preventable. Check your tire pressure (including the spare!), oil levels, and coolant. If you’re pushing the limits on your last inspection, get it handled before the long haul.

2. Review Your Roadside Assistance
Does your current auto policy include roadside assistance? Knowing you have a professional jump-start or a tow just a phone call away provides immense peace of mind. If you aren’t sure what your limit is for towing mileage, contact us to double-check your coverage.

3. The “Out of State” Factor
Insurance requirements vary by state. While your policy generally follows you, an accident far from home can be complicated. Ensure your digital insurance cards are downloaded to your phone (don’t rely on spotty mountain cell service!) and that you have a physical copy in the glovebox.

4. Consider an Umbrella Policy
If you are traveling with a group or driving a larger vehicle, such as an RV, your liability risks increase. An Umbrella Policy is an incredibly affordable way to add an extra $1 million (or more) of protection over your existing auto limits. It’s the ultimate “safety net” for frequent travelers.

5. Secure Your Home Base
A road trip is only relaxing if you know your home is safe.
Smart Tech: Check that your doorbell cameras are active.
Water Safety: Consider turning off the main water valve to prevent a surprise leak while you’re away.
Social Media: Wait until you’re back to post those vacation photos!

Contact us today for a quick policy review, or request a free quote online to ensure your summer memories are protected.

Safe travels and enjoy the ride!

4 Ways to Cut Your Insurance Costs Without Losing Coverage

If you just opened your insurance renewal and felt a bit of “sticker shock,” you aren’t alone. Between the rising cost of high-tech car parts and the increased price of home building materials, 2026 has been a tough year for the household budget.

While you can’t control the economy, you can control how much you pay for protection. Here are four ways to fight back against rising costs right now.

1. Let Your Driving Do the Talking (Telematics)
In 2026, the most effective way to lower your auto premium is to prove you’re a safe driver. Most carriers now offer Telematics programs—usually a simple smartphone app or a small plug-in device.

How it works: The app monitors things like smooth braking, speed, and whether you use your phone while driving.

The Benefit: Instead of paying a “generic” rate based on your zip code or age, you get a personalized discount. Many drivers are seeing savings of 20% to 40% just by proving they are low-risk.

The Myth: No, they aren’t “spying” on your grocery runs; they are looking for patterns that prove you won’t cost them a claim.

2. Find Your Deductible “Sweet Spot”
With the cost of living up, every dollar in your monthly budget counts. One of the fastest ways to lower that monthly bill is to adjust your deductible.

The Strategy: If you have an emergency fund tucked away, moving your auto deductible from $500 to $1,000, or your home deductible to $2,500, can slash your annual premium significantly.

The Win: You trade a small amount of risk for a guaranteed monthly “raise” in your take-home pay.

3. The “Smart Home” Payback
In 2026, insurance companies are terrified of water damage (it’s now one of the most common and expensive claims).

The Strategy: If you’ve installed a smart leak detector or a monitored security system, tell your agent immediately.

The Win: These devices do the work for the insurance company by preventing disasters before they happen, and many carriers are now mandated to offer “Mitigation Discounts” in return.

4. Optimize Your “Multi-Policy” Bundle
Most people know that bundling home and auto saves money, but in 2026, the “Advanced Bundle” is where the real savings are.

The Strategy: Check if adding a small Umbrella policy or even a Life insurance policy triggers a deeper “Tiered Discount” on your primary home and auto lines.

The Surprise: Sometimes, adding a small $20/month life policy can actually lower your total monthly bill because it unlocks a higher discount bracket for your home and cars.

The 2026 Cost-of-Living Checklist
Before you pay your next premium, ask yourself:

[ ] Is my driving being tracked for a discount?

[ ] Have I updated my agent on my new home security or smart-tech?

[ ] Is my deductible set for 2024 prices instead of 2026 realities?

Contact HomeSale Insurance Services at 800-425-5130 for a free quote and peace of mind today!

Why Restoration Quality Matters More Than Age in Classic Car Insurance

Restoration Quality Defines a Classic Car’s True Risk Profile

When it comes to classic car insurance, age alone no longer tells the full story. Two vehicles from the same model year can present very different risk levels depending on how they were restored. Insurance carriers increasingly focus on restoration quality because it directly affects safety, reliability, and repair outcomes. At HomeSale Insurance Services in Lancaster, PA, this distinction is a key part of how classic car coverage is evaluated.

Why Build Quality Matters More Than Model Year

A well-restored classic vehicle benefits from modern techniques, improved materials, and precise workmanship. Properly installed electrical systems, reinforced frames, and professionally rebuilt engines reduce the likelihood of mechanical failure. In contrast, poorly documented or rushed restorations can introduce hidden risks, regardless of how old the vehicle is. This is why insurers prioritize condition and craftsmanship over age when reviewing classic car policies.

Documentation Plays a Major Role in Coverage Decisions

High-quality restorations usually come with detailed records, including photos, invoices, parts lists, and timelines. These documents help establish an accurate agreed value and streamline claims if damage occurs. Classic cars without restoration documentation can be harder to insure properly, especially if replacement parts or specialty labor are involved. HomeSale Insurance Services in Lancaster, PA often helps collectors organize this information before coverage is finalized.

Restoration Quality Affects Repair Outcomes After a Claim

If a classic car is damaged, restoration quality influences how easily repairs can be completed. Vehicles restored with authentic parts and professional techniques are more likely to be repaired to pre-loss condition. Poor restorations may require additional corrections during repairs, extending timelines and complicating claims. This reality makes build quality a practical concern for insurers, not just an aesthetic one.

Modern Restorations Reflect How Classics Are Used Today

Many classic cars are no longer static showpieces. Owners drive them to events, tours, and regional shows. Insurers recognize this shift and evaluate whether restorations support safe, regular use. Updated braking systems, modern wiring, and improved cooling components often strengthen insurability. Reviewing restoration details with an experienced agency helps align coverage with real-world use.

Working With a Local Agency That Understands Collectors

Classic car insurance works best when coverage reflects the vehicle’s true condition. Restoration quality provides a clearer picture than age alone. To learn more about protecting your collector vehicle, visit HomeSale Insurance Services and explore classic car insurance guidance tailored for Pennsylvania collectors.

Affordable Pet Insurance for Your Family

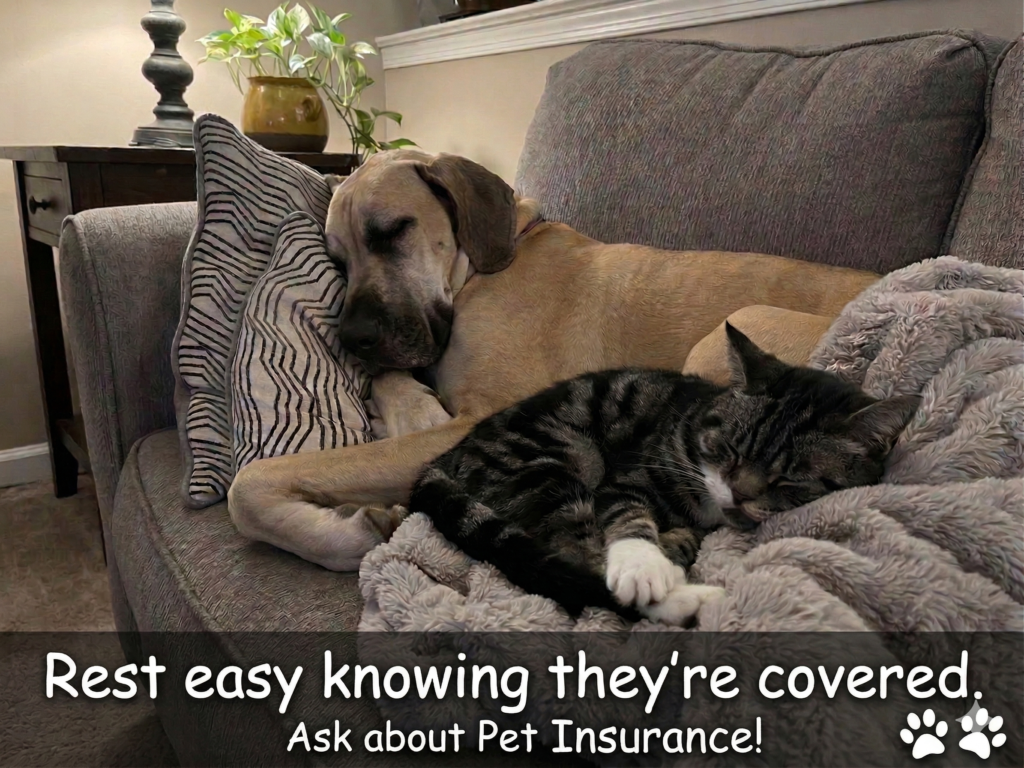
Marley and Scotty are family. Ensure they get the best care with pet insurance. Call 800-425-5130 for a free quote and peace of mind today!

Rest Easy: Affordable Pet Insurance for Your Family

Marley and Scotty are more than just pets; they are members of the family. For Instance, whether it’s a Great Dane sprawling across the sofa or a tabby cat nestled on the couch beside her, our animals bring a unique joy to our homes. However, that joy often comes with the responsibility of managing their health and wellness.

Why Pet Insurance Matters

Many pet owners assume they can handle vet bills as they come. Additionally, while routine checkups are predictable, emergencies rarely are. Whether it’s a sudden illness or an unexpected injury, the cost of veterinary care can escalate quickly. By securing a comprehensive policy, you ensure that financial constraints never stand in the way of your pet’s life-saving treatment.

Specifically, pet insurance can help cover:

  • Accidents and Injuries: From broken bones to swallowed objects.
  • Chronic Conditions: Ongoing care for issues like allergies or arthritis.
  • Diagnostic Tests: X-rays, MRIs, and bloodwork that can be costly.

Peace of Mind for Your Household

Furthermore, having insurance allows you to focus on what matters most: your pet’s recovery. According to the American Veterinary Medical Association (AVMA), having a plan in place is one of the best ways to be a proactive pet owner.

Don’t wait for an emergency to happen. Ensure Marley, Scotty, and the rest of your furry family get the best care possible.

Contact HomeSale Insurance Services at 800-425-5130 for a free quote and peace of mind today!

How Recreational Insurance Works When Borrowing or Lending Equipment to Family and Friends

Why Borrowing and Lending Recreational Equipment Can Create Insurance Confusion

In Lancaster, PA, it is common for friends and family to share recreational equipment like ATVs, boats, campers, or utility trailers. While borrowing gear can be convenient, it often raises questions about insurance responsibility when something goes wrong. Recreational insurance is not always as straightforward as people assume, especially when the person using the equipment is not the owner. HomeSale Insurance Services helps Lancaster residents understand how recreational coverage applies in these real-world situations.

How Recreational Insurance Typically Responds

In many cases, recreational insurance follows the vehicle or equipment rather than the person using it. This means the owner’s policy is often the first line of coverage if damage or an accident occurs. However, coverage depends on how the policy is written, what type of equipment is involved, and whether the borrower meets policy conditions. Some policies limit coverage when equipment is loaned out or used outside normal expectations.

Liability Risks When Friends or Family Are Involved

Liability exposure is one of the biggest concerns when lending recreational equipment. If someone is injured or property is damaged, the owner of the ATV, boat, or camper may still be held financially responsible. This is especially important in Pennsylvania, where recreational activities often take place on private land, campgrounds, or shared spaces.

  • Accidents caused by inexperienced operators
  • Injuries to passengers or bystanders
  • Damage occurring away from the owner’s property

Why Assumptions About Coverage Can Lead to Gaps

Many people assume that a borrower’s personal insurance will automatically apply, but that is not always the case. Auto policies, homeowners insurance, or renters coverage may offer limited or no protection for recreational equipment. Without proper recreational insurance, both the owner and the borrower could face uncovered losses.

How Local Guidance Makes a Difference

Working with a local agency helps ensure your coverage matches how your equipment is actually used. HomeSale Insurance Services in Lancaster, PA reviews recreational policies with real-life situations in mind, including shared use among trusted family and friends. Their team helps clarify liability limits, usage restrictions, and coverage expectations before an accident happens.

Sharing recreational equipment should be enjoyable, not stressful. To learn more about protecting your recreational vehicles and equipment, visit HomeSale Insurance Services and explore recreational insurance solutions designed for Lancaster lifestyles.

Moving from PA to MD? Your Complete Guide to Insurance Changes

Moving from Pennsylvania to Maryland? Learn exactly how to handle your auto insurance, home insurance, MVA inspections, and excise taxes to avoid penalties.

Moving across state lines is an exciting milestone, but transitioning between Pennsylvania and Maryland comes with specific regulatory hurdles that can catch drivers and homeowners off guard. At Homesale Insurance, we serve clients from Harrisburg and Lancaster all the way down to Westminster and the Baltimore suburbs. We know this corridor intimately.

If you’re asking, “What happens to my insurance when I move from PA to MD?”—here is your complete, step-by-step guide.

1. The 60-Day MVA Window (Do Not Miss This)

When you establish residency in Maryland, you have exactly 60 days to register your vehicle with the Maryland Motor Vehicle Administration (MVA). If you fail to do this, you risk facing a penalty tax of 6% of your vehicle’s current value.

Before you go to the MVA, you must have a valid Maryland auto insurance policy in place. Maryland requires your insurance provider to electronically verify your coverage with the state.

2. The Maryland Safety Inspection

Unlike Pennsylvania’s annual safety and emissions inspections, Maryland requires a one-time, highly rigorous safety inspection when you bring an out-of-state vehicle into the state.

  • Action Step: You must pass this inspection at a licensed Maryland inspection station before you can get your hard plates. Your Homesale Insurance agent can help you time your policy start date perfectly to align with your inspection schedule.

3. Auto Insurance Minimums: PA vs. MD

When you switch your policy, you will notice differences in coverage minimums.

  • Pennsylvania: Requires $15,000 for injury/death of one person, $30,000 for injury/death of more than one person, and $5,000 for property damage. PA also utilizes a “Choice No-Fault” system (Limited vs. Full Tort).
  • Maryland: Requires higher minimums: $30,000 for injury/death of one person, $60,000 for injury/death of two or more people, and $15,000 for property damage. MD operates under a traditional “At-Fault” system.

Because of the shift from No-Fault to At-Fault, and the increased minimums, it is critical to have an independent agent shop your rates to ensure your premium doesn’t spike.

4. Homeowners Insurance: Inland PA vs. Coastal MD

If you are moving from a central PA city like Carlisle or Camp Hill down toward the Chesapeake Bay or Ocean City, your home insurance risk profile changes completely.

  • Wind and Water: Properties on the water or very close to the Chesapeake Bay or Ocean City, Maryland are often subject to different windstorm deductibles and flood risks compared to central PA. Standard homeowners insurance does not cover flooding. If your new MD home is in a flood zone, we will need to secure a separate policy through the National Flood Insurance Program (NFIP) or a private carrier.

Let Us Handle the Transition

Dealing with the MVA and closing on a new house is enough work. You don’t need to spend hours on hold with 1-800 numbers trying to coordinate your policy switch. Because Homesale Insurance is licensed and deeply embedded in both PA and MD, we can seamlessly cancel your PA policies and bind your MD policies on the exact day you need them.

Contact Homesale Insurance today for a free state-to-state transition review.

Do I Really Need Motorcycle Insurance for Short Rides?

In Lancaster, PA, many people who ride a motorcycle enjoy quick trips through town or along familiar backroads. Because these outings feel short and predictable, bikers often search online for answers about whether full motorcycle insurance is really necessary. It is a common question, especially when the motorcycle is not used for long commutes or weekend travel. HomeSale Insurance Services helps local motorcyclists understand why protection still matters, even during quick outings.

Why Short Trips Still Come With Risks

Even brief trips come with unexpected hazards. Most accidents happen close to home, and Lancaster traffic, sudden stops, and distracted drivers can create challenges for bikers. Road debris, uneven pavement, or weather changes can also lead to damage. Motorcycle insurance helps support people who ride a motorcycle when surprises occur, regardless of how short the route may be.

Coverage That Supports Motorcyclists in Everyday Situations

Many motorcyclists search for explanations about what different coverages actually do. Liability protection helps if someone else’s property is damaged. Collision coverage can assist with repairing the motorcycle after an accident, while comprehensive coverage helps when damage results from something other than a crash. Working with
HomeSale Insurance Services helps Lancaster, PA bikers understand how each type of coverage fits the way they use their motorcycle.

Why Gear and Accessories Need Protection Too

Every outing, even a short one, usually involves important safety gear. Helmets, jackets, gloves, and custom motorcycle parts can be expensive to replace. Motorcycle insurance can help protect these items when unexpected drops, minor accidents, or other sudden issues occur. This coverage is especially useful for people who have invested in high-quality safety gear or customized their motorcycle.

Staying Prepared for Every Season

Whether a person heads out for five minutes or fifty miles, the right insurance protection makes a difference during unexpected events. Reviewing coverage, updating details at the start of each season, and asking important insurance questions can help keep bikers prepared. With help from
HomeSale Insurance Services, motorcyclists in Lancaster, PA can ride confidently knowing their protection matches the way they use their motorcycle.

The Maryland to Pennsylvania Insurance Checklist: 5 Gaps You Must Close

Moving across the Mason-Dixon line involves more than just a new zip code. Pennsylvania’s insurance landscape operates differently than Maryland’s, particularly regarding your “Right to Sue” in auto accidents and unique regional property risks like sinkholes. Use this checklist to ensure your coverage crosses the border safely.

1. The Auto Insurance “Tort” Choice (The Biggest Change)

In Maryland, you have an unrestricted right to seek compensation after an accident. In Pennsylvania, you must choose a “Tort Option.”

  • Select Full Tort vs. Limited Tort:
    • Full Tort: Maintains your unrestricted right to sue for pain and suffering.
    • Limited Tort: Lowers your premium but restricts your legal rights unless the injury is “serious” as defined by law.
  • Update Your Medical Benefits (PIP): PA requires a minimum of $5,000 in Medical Benefits. This is a mandatory coverage.
  • PA Vehicle Inspection & Registration: You have 20 days after titling your vehicle in PA to get it inspected. Your insurance must be active and PA-specific before you can register the vehicle.

2. Homeowners Insurance: The “Ground” Factor

Maryland’s coastal and suburban risks differ from Pennsylvania’s limestone-heavy geography.

  • Add Sinkhole Coverage: If you are moving to Lancaster, York, or the Cumberland Valley, you are in a high-risk area for sinkholes. Standard homeowners policies exclude earth movement. Ask for a specific Sinkhole Endorsement.
  • Check for Mine Subsidence: Moving toward Western PA or specific parts of Schuylkill County? You may need Mine Subsidence Insurance (MSI).
  • Water Backup/Sump Pump Overflow: With PA’s older infrastructure and basement-heavy homes in Lancaster and Reading, ensure you have a water backup coverage.

Common Questions About Moving Insurance from MD to PA:

  • Do I need a new insurance agent when moving from MD to PA? Maybe. Your agent must be licensed in the state where the risk (your home or car) is located. Homesale Insurance is licensed in both PA and MD, making us the ideal “border-crossing” partner.
  • Is insurance cheaper in PA or MD? It varies by zip code. While MD often has higher liability costs in metro areas like Baltimore, PA’s “Tort” system and specific regional risks like sinkholes can impact your premium.

Contact one of our Homesale Insurance Advisors today. We are ready to help you with your move from Maryland to Pennsylvania. 800-425-5130. You can also click on the QR code below to get started.

Buying a Historic Home in Lancaster? 3 Insurance Gaps That Could Cost You.

Walking through the streets of Lancaster City or Lititz, you’ll often see those iron “Fire Marks” on old brick facades. Back then, they were a guarantee that fire brigades would save your home. Today, protection is a bit more complex. If you are buying a home built before 1940, a standard policy might leave you exposed.

1. The “Rebuild” vs. “Repair” Trap Many insurers provide replacement cost coverage. This will pay for the cost to replace/rebuild your home if it was damaged. But in Lancaster, replacing hand-carved molding, slate roofing, or horse-hair plaster is very unique and not typically seen in modern houses. you might need extended dwelling coverage or functional replacement cost

2. The “Hidden” Systems (Knob & Tube) We love the charm of exposed brick, but we hate what’s often behind it: Knob and Tube wiring. Many carriers will flat-out refuse to insure it due to fire risk. At Homesale Insurance, we know which carriers specialize in historic PA homes and can help you navigate inspection requirements without losing the deal.

3. The Sinkhole Reality Pennsylvania sits on limestone, making us one of the top states for sinkhole activity. Standard home insurance does typically does cover earth movement. You could be fully financially responsible for the repairs—unless you have a specific Sinkhole Endorsement.

Lancaster FAQ

  • Q: Do I really need sinkhole insurance in Lancaster County?
    • A: Yes. Pennsylvania is prone to sinkholes due to our limestone bedrock (karst terrain). Standard home policies exclude “earth movement.” We highly recommend adding a specific Sinkhole Endorsement to protect your foundation.
  • Q: Does my auto insurance cover horse and buggy accidents?
    • A: Yes, a collision with a buggy is treated like a collision with another vehicle. However, given the severity of these accidents, we recommend higher limits to protect your assets from lawsuits.
  • American Modern Insurance Group
  • Assurant Flood
  • Berkshire Hathaway Guard Ins Co
  • Chesapeake Employers Insurance
  • Chubb & Son Inc./ACE
  • Donegal Insurance
  • Encompass Insurance Co
  • Farmers of Salem
  • Foremost
  • Foremost Specialty
  • Frederick Mutual Insurance Co
  • Grange Insurance Group
  • Liberty Mutual Insurance Company
  • Lititz Mutual
  • millers mutual
  • Narragansett Bay Insurance CO
  • Nationwide
  • Openly
  • Phila Contributionship Ins
  • Plymouth Rock Assurance
  • Progressive
  • RLI
  • Travelers
  • USLI
  • Westfield Insurance Company
  • Wright Insurance Group

Peace of Mind

With HomeSale Insurance Services, get fast, reliable, online quotes for your
insurance peace of mind.

Get Started!